MyCard - Contactless Payment

Screenshots
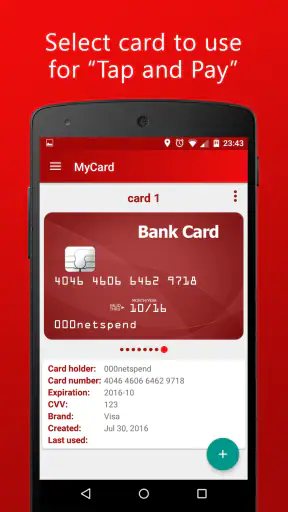
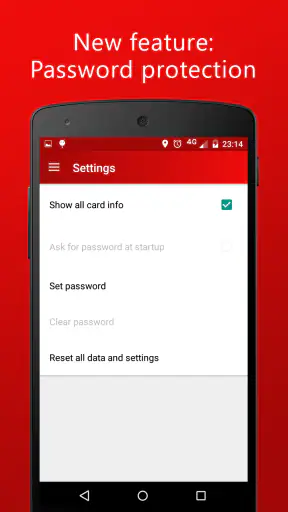
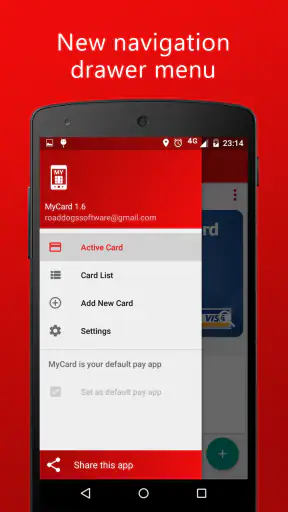
Details
- Rating
- 120.00 reviews
- Version
- 1.21
- Developer
- Road Dogs
Analysis by Norviv
I approached MyCard - Contactless Payment as a practical finance tool rather than as a replacement for every banking app. Its purpose is narrow and easy to understand: it turns a compatible phone into a contactless bank card. That focus can be useful when I want to pay without taking out a physical card, but it also means the experience depends heavily on the phone, the payment terminal, and the way a person normally manages money.
Developed by Road Dogs, this paid finance app costs $17.99 and is aimed at Everyone. It has been available since March 22, 2016, and version 1.21 supports devices running Android 5.0 or later. Its store summary presents it as an NFC mobile payment app, while the short description simply calls it MyCard. Those details tell me what the app is trying to do, but the real question is whether that single purpose fits my daily routine and the way I interact with a phone.
How MyCard feels to use in everyday payment situations
I find the everyday appeal of MyCard less about novelty and more about making one small part of a checkout routine predictable: paying with a phone instead of reaching for a bank card. That convenience works best when I prepare before joining the queue and know how I’ll confirm the payment. From there, it’s worth looking at the situations where that routine is genuinely helpful—and where a physical card remains the easier choice.
Readability and navigation before I reach the terminal
The strongest part of a focused payment app is usually its limited scope. I do not expect to browse investment products, inspect spending charts, or manage a complete bank account here. For someone who only wants to prepare a phone for contactless payment, that narrower approach can reduce distraction. There are fewer kinds of tasks to understand, and the central idea is much clearer than it would be in a full banking application.
That simplicity matters for people who find crowded financial software tiring. A banking app may place transfers, statements, cards, alerts, offers, and account settings on the same screen. A dedicated contactless tool has a more direct job. In my view, MyCard makes the most sense when I already understand my card and account, and I want the phone to act as the payment interface rather than as a complete financial dashboard.
At the same time, a simple purpose does not automatically guarantee easy navigation for everyone. Payment setup is a high-consequence task: a vague instruction, an unclear status, or a missed confirmation can leave me unsure whether I am ready to pay. I would take time to read each screen instead of tapping quickly, especially before using the app in a busy shop. That habit is more important here than speed.
Text size, contrast, spacing, and the clarity of labels can make a large difference to someone with reduced vision or reading fatigue. I would test the app with the phone’s own display settings and check whether the important controls remain understandable at a larger text size. If increasing text makes buttons disappear, overlap, or become difficult to reach, the app becomes less suitable even if the basic payment idea is convenient.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
There is also a useful distinction between reading information at home and reading it at a checkout. At home, I can pause and inspect a setup screen. In a queue, I may have only a moment to confirm that the phone is ready. My practical advice is to complete the initial configuration before going shopping, then rehearse the final steps without a live transaction. That avoids turning the first real payment into an accessibility test under pressure.
Motor and sensory considerations when paying
Contactless payment can remove several physical actions associated with a wallet. I do not have to pull out a card, position it in a reader, or put it away again. For someone with limited dexterity, tremor, joint pain, or difficulty handling small objects, using one phone may be easier than manipulating a card and wallet together. The benefit is not universal, but it is a meaningful reason to consider this kind of app.
The phone itself can still create friction. I need to grip it securely, bring it close enough to the terminal, and keep it in a useful position while the transaction is processed. A large or heavy phone may be harder to hold than a bank card. A person who has difficulty with precise hand movements may prefer a case, grip, or mounting arrangement that makes the device safer to handle, although that choice is personal and not something the app can solve.
For users with limited hearing, a payment flow should not depend only on a sound from the terminal or the phone. I would look for a visible confirmation and watch the terminal display as well. Conversely, someone sensitive to sudden sounds or busy visual environments may appreciate being able to concentrate on the screen and the physical reader instead of relying on an audible signal. The important point is to use more than one cue whenever possible.
People with sensory processing differences may also find the checkout environment more difficult than the app itself. Bright displays, queue pressure, background noise, and a cashier waiting for a response can make a short interaction feel complicated. I would prepare the phone before reaching the counter and avoid opening unrelated apps at the last moment. A predictable routine—unlock, present, wait for confirmation—can reduce decision-making when the surroundings are overwhelming.
One non-obvious trade-off is that removing the physical card does not remove the need for a reliable backup. If the phone is difficult to hold, the battery is low, or the terminal does not respond as expected, a second payment method can prevent a stressful situation. I would keep a physical card or another agreed alternative available, particularly when travelling, shopping alone, or paying for something essential.
Situational access: where the phone-based approach helps
MyCard is most appealing in everyday places where contactless terminals are already part of the checkout routine. A quick purchase at a supermarket, café, or transport-related counter can be easier when I can leave the wallet in my pocket and present the phone. This is especially useful when my hands are occupied with a bag, walking aid, or other item, provided I can safely hold and position the phone.
Consider a realistic example: I am carrying groceries and do not want to search through a crowded bag for a card. Before joining the queue, I prepare the phone so I am not trying to navigate while the cashier waits. At the terminal, I bring the device close, watch for the visible result, and keep my backup payment method available. The app can make that moment smoother, but the smoothness comes from preparation as much as from the software.
The same workflow can help a person who has difficulty remembering where a physical card was placed. A phone is often already carried and easier to locate through a consistent routine. That does not mean it is automatically more secure or more accessible for every person; it means the phone may fit better into an established daily habit.
There are situations where the usual alternative is better. If I need cash, want to compare several accounts, review a detailed statement, or manage a card dispute, I would use my bank’s app or speak with the bank instead. MyCard’s focused payment role should not be mistaken for a replacement for those services. A physical card may also be preferable at a terminal that behaves unpredictably, in a place with weak phone access, or whenever handling the phone is harder than handling plastic.
Travelling adds another layer of uncertainty. I would not assume that every country, bank, or terminal treats a phone payment in exactly the same way. Before relying on it away from home, I would test it locally and carry a backup. This is not a criticism of Road Dogs specifically; it is a sensible rule for any payment method that depends on a particular device and contactless infrastructure.
What the current app profile suggests about practical fit
MyCard has an average rating of 4.0 from around 286 ratings, with about 120 written reviews, and it has passed 10K+ installs. Those figures suggest that it has attracted a real group of users, while also leaving room for mixed experiences. I read that combination as a reason to judge the app against my own phone, bank, and payment habits rather than treating the rating as a guarantee.
The price deserves careful thought. At $17.99, this is not an impulse download for someone who only wants to experiment with phone payments once. I would first ask whether contactless payment solves a recurring problem for me: carrying a wallet is difficult, reaching a card is inconvenient, or I want a more consistent payment routine. If the answer is no, the cost may be harder to justify than it would be for a person who expects to use the app frequently.
The age rating of Everyone makes the app broadly approachable from a content perspective, but that does not mean every child or adult can independently use a payment tool safely. Financial responsibility, account ownership, device access, and support from a trusted person matter more than the label alone. I would be particularly cautious about setting it up for someone who has difficulty recognizing payment confirmations or understanding when a transaction has completed.
The minimum operating system of Android 5.0 gives the app a relatively broad technical starting point, and the current version is 1.21. Still, an older compatible operating system does not tell me how comfortable the experience will be on every device. Screen size, manufacturer settings, NFC hardware, security configuration, and the phone’s general condition can all affect the practical result. I would test the complete payment flow on the exact phone that will be used, not on a different device.
Remaining barriers I would want to check first
The biggest barrier is dependence on the phone as both the tool and the object I must operate. A person may have difficulty unlocking a device, locating the payment app, holding the phone near the reader, or interpreting the result. Someone with limited vision may need larger text or stronger visual confirmation. Someone with limited dexterity may need a stable grip. Someone with cognitive disabilities may benefit from a simple, repeated routine and help during setup.
Another barrier is uncertainty at the terminal. Contactless readers vary in position and response time, and a busy checkout does not always offer space to troubleshoot. I would learn where the phone’s NFC area works best and practice with a trusted retailer if possible. The goal is not to memorize a technical specification; it is to avoid repeatedly sweeping the phone around while the terminal times out.
Security and privacy also deserve a calm, practical discussion. A phone-based payment tool should be treated as a financial instrument, not as an ordinary utility. I would use a device lock, avoid handing the unlocked phone to another person, and check the payment result before walking away. If a trusted helper assists with setup, I would make sure the account and payment decisions remain under the correct person’s control.
Support is another consideration for users who need accessible help. I would not choose MyCard solely because its task sounds simple. I would first check whether the app works with my phone’s accessibility settings and whether I can recover from a failed or interrupted payment without assistance. If I cannot clearly identify what happened after a declined or incomplete attempt, the app is not ready to be my only payment method.
People who rely on screen readers should test the actual setup and payment controls rather than assuming that a small app will be fully compatible. The same applies to magnification, voice control, switch access, and alternative input methods. These tools can improve the phone experience, but their usefulness depends on how the app exposes labels and controls. I would make the decision after a hands-on trial, not from the general promise of contactless payment.
Who should choose it, and who should skip it
I would recommend MyCard to someone who already has a compatible Android phone, regularly encounters contactless terminals, and values carrying one less physical item. It is also worth considering for a user who can complete a short, repeatable payment routine and who has a backup for unusual situations. The app’s focused finance role may be more comfortable than opening a large banking application just to pay.
I would be more hesitant for someone who wants a full account-management tool, needs extensive transaction history, prefers cash, or cannot reliably operate a phone at a terminal. I would also skip it as a sole payment method if the price is difficult to justify or if my bank and device setup are not already comfortable with contactless use. In those cases, a physical card or the bank’s established mobile solution may be the better choice.
For a household supporting an older adult or a person with disabilities, I would make the decision together rather than installing it and assuming the problem is solved. The useful questions are practical: Can the person see the important status clearly? Can they hold the phone safely? Can they tell a completed payment from a failed one? Can they access a backup without embarrassment or delay? Those answers matter more than the app’s category.
My inclusive verdict after weighing convenience against control
MyCard offers a clear idea with a potentially meaningful accessibility benefit: replacing several wallet-handling steps with a phone-based contactless payment routine. For some people, that is a real improvement in independence. The app is most convincing when the phone is already easy to operate and the user wants a dedicated way to pay rather than another all-purpose banking dashboard.
Its limitations are equally important. The experience still depends on grip, vision, device settings, terminal placement, payment confirmation, and a reliable backup plan. The Everyone rating should not be read as a promise that every ability level will find the app effortless. I would treat accessibility as something to verify through the exact phone and routine I intend to use.
With an average rating of 4.0 and a focused purpose, the app looks like a reasonable option for a specific group rather than an automatic recommendation for everyone. The $17.99 price makes frequent use especially important. I would choose it when contactless phone payments solve a genuine daily barrier, test it carefully before relying on it, and keep another payment method available. For that audience, the best feature is the reduction of wallet handling, not the novelty of paying with a phone.
Frequently Asked Questions
01What is MyCard - Contactless Payment and how does it work?
MyCard - Contactless Payment is designed to let users make payments by tapping a compatible smartphone or device at supported contactless terminals. After installing the app, you generally need to add or connect an eligible payment card, complete identity or security verification, and follow the setup instructions. Availability and exact features may depend on your country, bank, card issuer, and device compatibility.
02Is MyCard - Contactless Payment safe to use for everyday purchases?
The app is intended to provide a convenient alternative to carrying a physical card, using device security and payment authentication features where supported. Before using it, enable a screen lock, biometric protection, or another available security method. You should also download the app only from an official store, keep your operating system updated, and contact your bank immediately if your phone or payment credentials are lost or used without permission.
03Which phones, cards, and payment terminals are compatible with MyCard?
Compatibility can vary considerably, so users should check the app’s current requirements before downloading or attempting setup. Your phone may need NFC support, a supported operating system version, and appropriate security settings. The payment card must usually be issued by a participating bank or provider, while the store terminal must accept the relevant contactless payment network. Rooted or modified devices may not be supported.
04Are there any fees for using MyCard - Contactless Payment?
Downloading or using a contactless payment app may be free, but that does not guarantee that every transaction is cost-free. Your bank, card issuer, mobile operator, or payment provider could apply foreign-exchange charges, cash-advance fees, account fees, or other costs depending on the transaction. Review the app’s terms and your card agreement carefully, especially when paying abroad or using a linked debit or credit card.
05What should I do if a contactless payment fails or my phone is lost?
If a payment fails, first check that NFC is enabled, the phone is unlocked when required, the correct card is selected, and the terminal supports contactless payments. Trying again or using the physical card may resolve a temporary issue. If your phone is lost or stolen, use your device’s remote-lock or erase tools, contact the bank or card issuer, and suspend or remove the linked payment credentials as soon as possible.


